Cross-border trade risk
Third-party intelligence for cross-border trade is the structured process of finding out who really sits behind a trade: who owns your customer, who your supplier is affiliated with, where the goods travel after they leave your hands, and who ultimately uses them. It goes beyond checking a company name against a list. It brings together ownership data, affiliations, adverse media and sanctions information so that analysts can identify potential risk indicators, and so that compliance and commercial teams can make informed decisions based on evidence rather than on what a counterparty chooses to disclose.
The need is sharpest where goods are re-exported or transhipped. Each additional hop adds a party you did not choose directly, and each of those parties can carry sanctions, fraud or reputational risk back to you. For businesses and financial institutions operating from the UAE, one of the region's most active trading hubs, understanding this indirect exposure is part of everyday due diligence rather than an occasional exercise.
DeepSearch Intelligence™ is an intelligence platform built for this work. It supports corporate investigations, risk analysis, compliance and due diligence, and it helps teams make informed decisions, with the final judgement always resting with people rather than software.
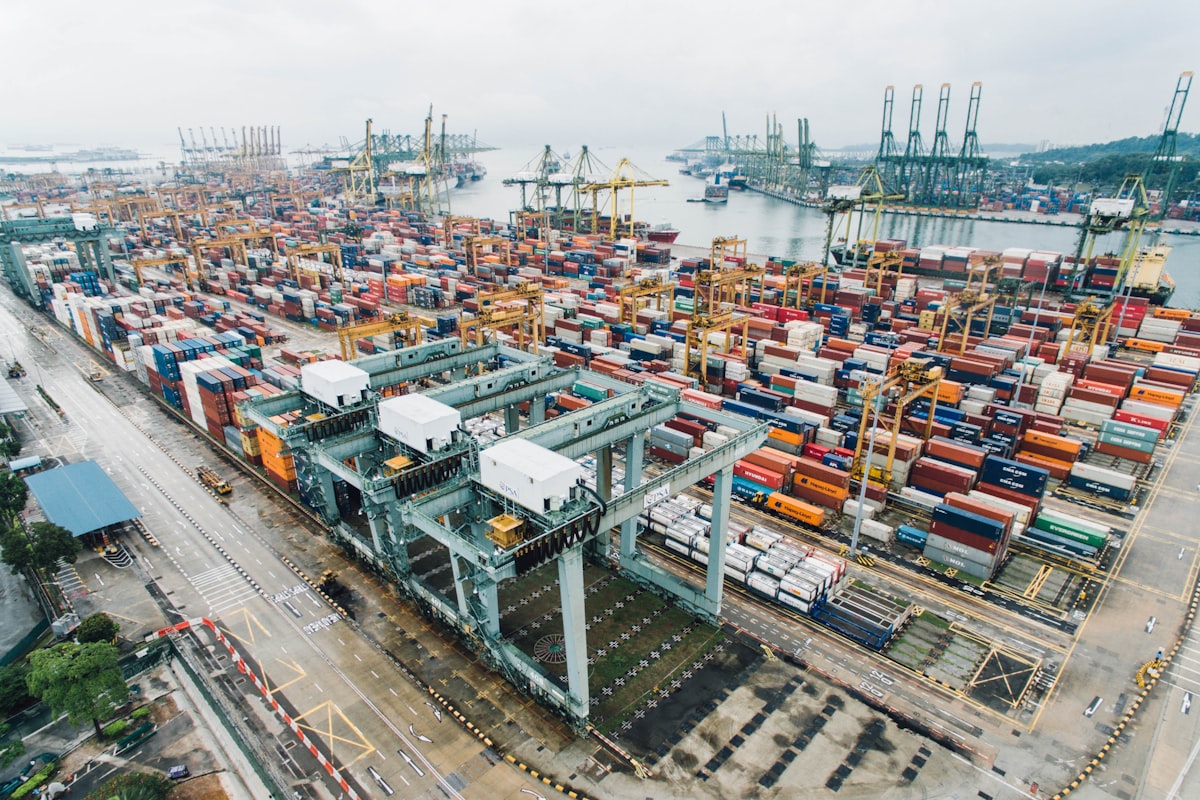
Goods are imported into one country and then sold and shipped on to another, often without substantial transformation. The first buyer becomes a seller, and the final destination may differ from the one named in your contract.
Cargo is moved from one vessel or conveyance to another at an intermediate port or hub on its way to a final destination. The goods pass through a location, but the commercial parties and the end point may sit somewhere else entirely.
Both are legitimate and common. Both also create distance between you and the end user, which is exactly the distance that diversion schemes, front companies and sanctions evasion rely on.
The UAE, and Dubai in particular, has a well-established re-export and transhipment sector, and neighbouring emirates are expanding theirs. That position brings volume and opportunity, and it also brings scrutiny: several foreign authorities list the UAE among the hubs where shipments involving sensitive goods warrant closer screening.
The Central Bank of the UAE has issued guidance for licensed financial institutions on trade-based money laundering and transhipment risk, which makes this topic a supervisory expectation for banks, not only a concern for exporters.
Indirect exposure
Indirect counterparty exposure arises when a risk sits one or more steps away from the party you contract with. Three illustrative patterns:
Your customer is not listed anywhere, but a layered holding structure leads to an owner who is subject to sanctions or is a politically exposed person.
A regional distributor buys in good order, then resells to a customer in a restricted jurisdiction, placing your goods in a destination you would never have approved.
A trading agent or forwarder alters consignee details or adds a transhipment point after the contract is signed, and payment starts arriving from an unrelated third country.
A counterparty, its owners, its officers or its vessels may be designated, or may be owned by designated persons even when the entity itself appears on no list.
Goods, funds or services may reach a country or region subject to embargoes, export controls or heightened regulatory concern.
Nominee shareholders, offshore vehicles and multi-layer holdings can obscure the natural persons who actually control a counterparty.
Goods declared for one destination or end use are redirected, often through re-export or transhipment, to a prohibited end user or destination.
Fictitious or altered documents, mis-invoicing and phantom shipments can move value under the appearance of legitimate trade.
Association with a party linked to corruption, evasion or organised crime can affect banking relationships, licences and investor confidence long after the trade closes.
A trade usually involves more parties than the contract names. A proportionate programme, the foundation of third party risk management in the UAE, covers at least these four groups:
The buying entity, its beneficial owners, directors and, where relevant, the party that actually pays.
Manufacturers and traders you buy from, including their ownership and the true origin of what they sell.
Agents, brokers, distributors, freight forwarders and other facilitators who can change routes, documents or payment flows.
The organisation that will ultimately use the goods, and the stated end use, which may differ from the first buyer.
Warning signs
One red flag rarely decides a case. Several together, or one that cannot be explained, justify a closer look.
| Data point | What to confirm | Why it matters in trade |
|---|---|---|
| Legal existence | Registration, licence status, registered address, date of incorporation | Separates operating businesses from shell or recently formed vehicles |
| Ownership and control | Shareholders at every layer, ultimate beneficial owners, directors and signatories | Helps analysts identify owners who may be sanctioned, politically exposed or linked to restricted parties |
| Affiliations | Group companies, common directors, shared addresses and related entities abroad | Helps surface networks that connect an apparently clean entity to a higher-risk one |
| Sanctions and PEP status | The entity, its owners, its officers and, where relevant, vessels and banks involved | Brings direct and ownership-based sanctions indicators into view |
| Adverse media and litigation | Reporting on fraud, corruption, evasion, enforcement actions and court cases | Highlights risk factors that have not yet reached any official list |
| Trade consistency | Business activity against goods ordered, route, destination, end use and payment flow | Helps reviewers judge whether the transaction makes commercial sense for this party |
Method
Name screening answers one question: is this name on a list today? Intelligence helps analysts answer the harder ones. Drawing on official government registers, public records and filings, open-source intelligence (OSINT) and trusted third-party providers, it assembles a fuller picture around a counterparty and records where each finding came from, so that specialists can review the evidence before anyone acts on it.
Under the US OFAC 50 Percent Rule, an entity owned 50 percent or more, in aggregate, by blocked persons is treated as blocked itself, even when its own name appears on no published list. Aggregation is what catches teams out: two minority holdings linked to the same designated person can cross the threshold together. How the rule applies to a specific transaction is a question for your legal advisers.
That is why ultimate beneficial owner screening across every layer of a structure is central to trade due diligence, not an optional extra.
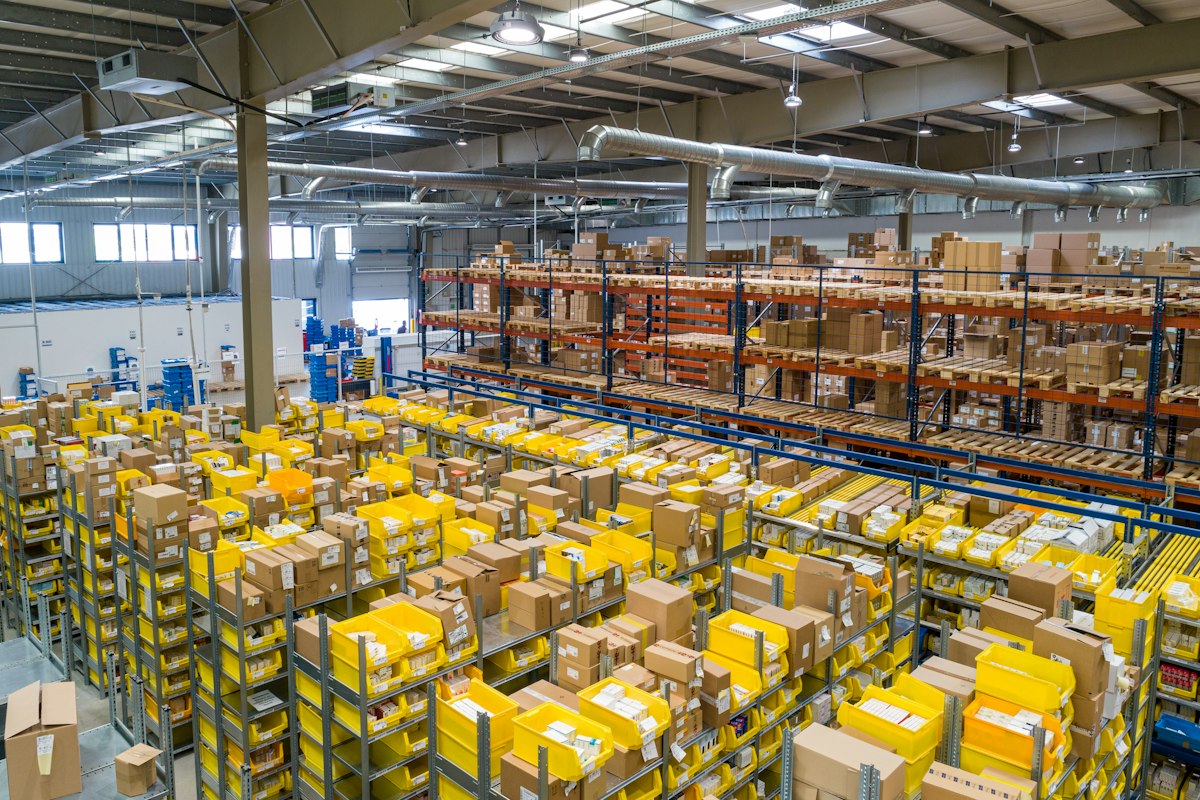
Stock held at a hub can change hands several times before it ships onward.

Documents are tested against ownership and route data, not read in isolation.
Before you ship or pay
Use it before accepting a new order, adding a new route or releasing payment. Record the outcome of each item and the source relied on, so the decision can be reviewed later.
Standard checks suit most low-risk trades. Enhanced due diligence is proportionate when the risk profile rises, typically in the situations below. Pairing it with your wider AML and KYC checks keeps the file consistent across onboarding and trade approval.
Intelligence informs a decision; it does not make it. The findings support a human reviewer who weighs them against the organisation's risk appetite and legal obligations. A structured outcome path helps keep those decisions consistent:
No material findings. Record the checks performed and set routine monitoring.
Manageable findings. Add end-use statements, contractual warranties, route restrictions or tighter monitoring.
Unresolved or serious findings. Refer to senior compliance or legal review and request further information before any shipment or payment.
Findings outside risk appetite. Document the rationale and, with your legal advisers, consider any reporting obligations that apply to your institution.
DeepSearch Intelligence™ is built for this human-in-the-loop model: people make the final decision, not the software. Reports are delivered online in real time with a full audit trail and role-based access, giving reviewers a traceable record behind every intelligence finding. The platform is designed with consideration for applicable data protection requirements, including the GDPR and Swiss FADP where relevant, and to support compliance workflows informed by applicable FATF principles and relevant UAE regulatory requirements and guidance.
Our commitments
Every intelligence finding we deliver is shaped by five principles that define what the platform does, and what it does not do.
Data comes from official government registers, public records and filings, open-source intelligence and trusted third-party providers.
The platform provides intelligence to support analysts, compliance officers and decision-makers, who review the findings.
DeepSearch Intelligence™ does not make automated decisions about any person, company or transaction.
DeepSearch Intelligence™ is not a law firm. It provides legal, regulatory and compliance intelligence, not legal advice or legal opinions.
Intelligence Assessments present risk indicators and findings for review. They are not legally binding risk assessments.
It is the structured gathering and analysis of information about the parties involved in an international trade, including customers, suppliers, intermediaries and end users. It covers ownership, affiliations, sanctions and PEP status, adverse media and litigation, so that analysts can identify potential risk indicators and decision-makers can act on traceable evidence.
Re-export means goods are imported into one country and then sold on to another. Transhipment means goods are moved between conveyances at an intermediate point on their way to a final destination. Both are lawful and common, and both can put distance between the original seller and the real end user.
The UAE, and Dubai in particular, is a major re-export and transhipment hub, and some foreign authorities name it among the locations where shipments of sensitive goods call for enhanced screening. The Central Bank of the UAE has also published guidance for licensed financial institutions on trade-based money laundering and transhipment risk.
Usually not. An entity can be unlisted yet owned or controlled by designated persons. Under the OFAC 50 Percent Rule, for example, an entity owned 50 percent or more in aggregate by blocked persons is itself treated as blocked. Ownership tracing, affiliation mapping and adverse media review help close that gap, and your legal advisers can confirm how the rule applies to a given case.
At a minimum, customers, suppliers, intermediaries such as agents, distributors and freight forwarders, and end users. Where relevant, also screen the party making payment if it differs from the buyer, and the owners and officers behind each entity.
When a trade involves high-risk jurisdictions, sensitive or controlled goods, opaque ownership, PEP or sanctions proximity, unresolved red flags, or significant value or reputational weight. Enhanced due diligence goes deeper on ownership, affiliations and media, and documents each step.
No. DeepSearch Intelligence™ is an intelligence platform that supports human decision-making. It provides structured, traceable intelligence findings drawn from 400+ million entities, with a full audit trail, and your specialists make the final decision to proceed, add conditions, escalate or decline. It does not make automated decisions or provide legal advice.
From official government registers, public records and public filings, open-source intelligence (OSINT) and trusted third-party providers. Each finding is traceable to its source, so reviewers can check the evidence behind it.
If you are weighing how much diligence a counterparty needs, the overview of four intelligence reporting levels sets out what each depth covers, from core screening to multi-jurisdictional review. When you are ready, you can request an Intelligence Assessment reviewed by our specialists.

